Power Rankings: CDC tops Australia’s data centre operators
By Winston Su, Editor · · Add us as a preferred source on Google
At a glance
CDC Data Centres leads the October 2026 Power Rankings, after 625MW of new contracts since May and the largest approved pipeline of the ten operators.
NEXTDC is second, from first in June, and leads all ten on capital closed in the past twelve months.
AirTrunk is third and leads on operating capacity. It secured a A$4.25 billion loan for SYD3 on 27 October 2026.
DigiCo rises from sixth to fourth after a 71MW, 15-year contract filled its SYD1 campus in Ultimo, and GreenSquare rises three places to sixth on a contract for its 15MW first stage at Norwest.
Goodman and DCI Data Centers are joint eighth, and Digital Realty is tenth.
The June 2026 Power Rankings placed NEXTDC first, AirTrunk second and CDC third, on a weighted mix of measures including scale, deliverability and momentum. This edition ranks ten operators on four measures that they and planning authorities have published, and covers the news since July operator by operator, including the DigiCo SYD1 contract, the AirTrunk SYD3 loan and the NEXTDC M3 power delay in Melbourne behind its guidance cut.
CDC Data Centres ranks first, leading on contracted and approved capacity, and NEXTDC is second on the strength of the capital it has raised.
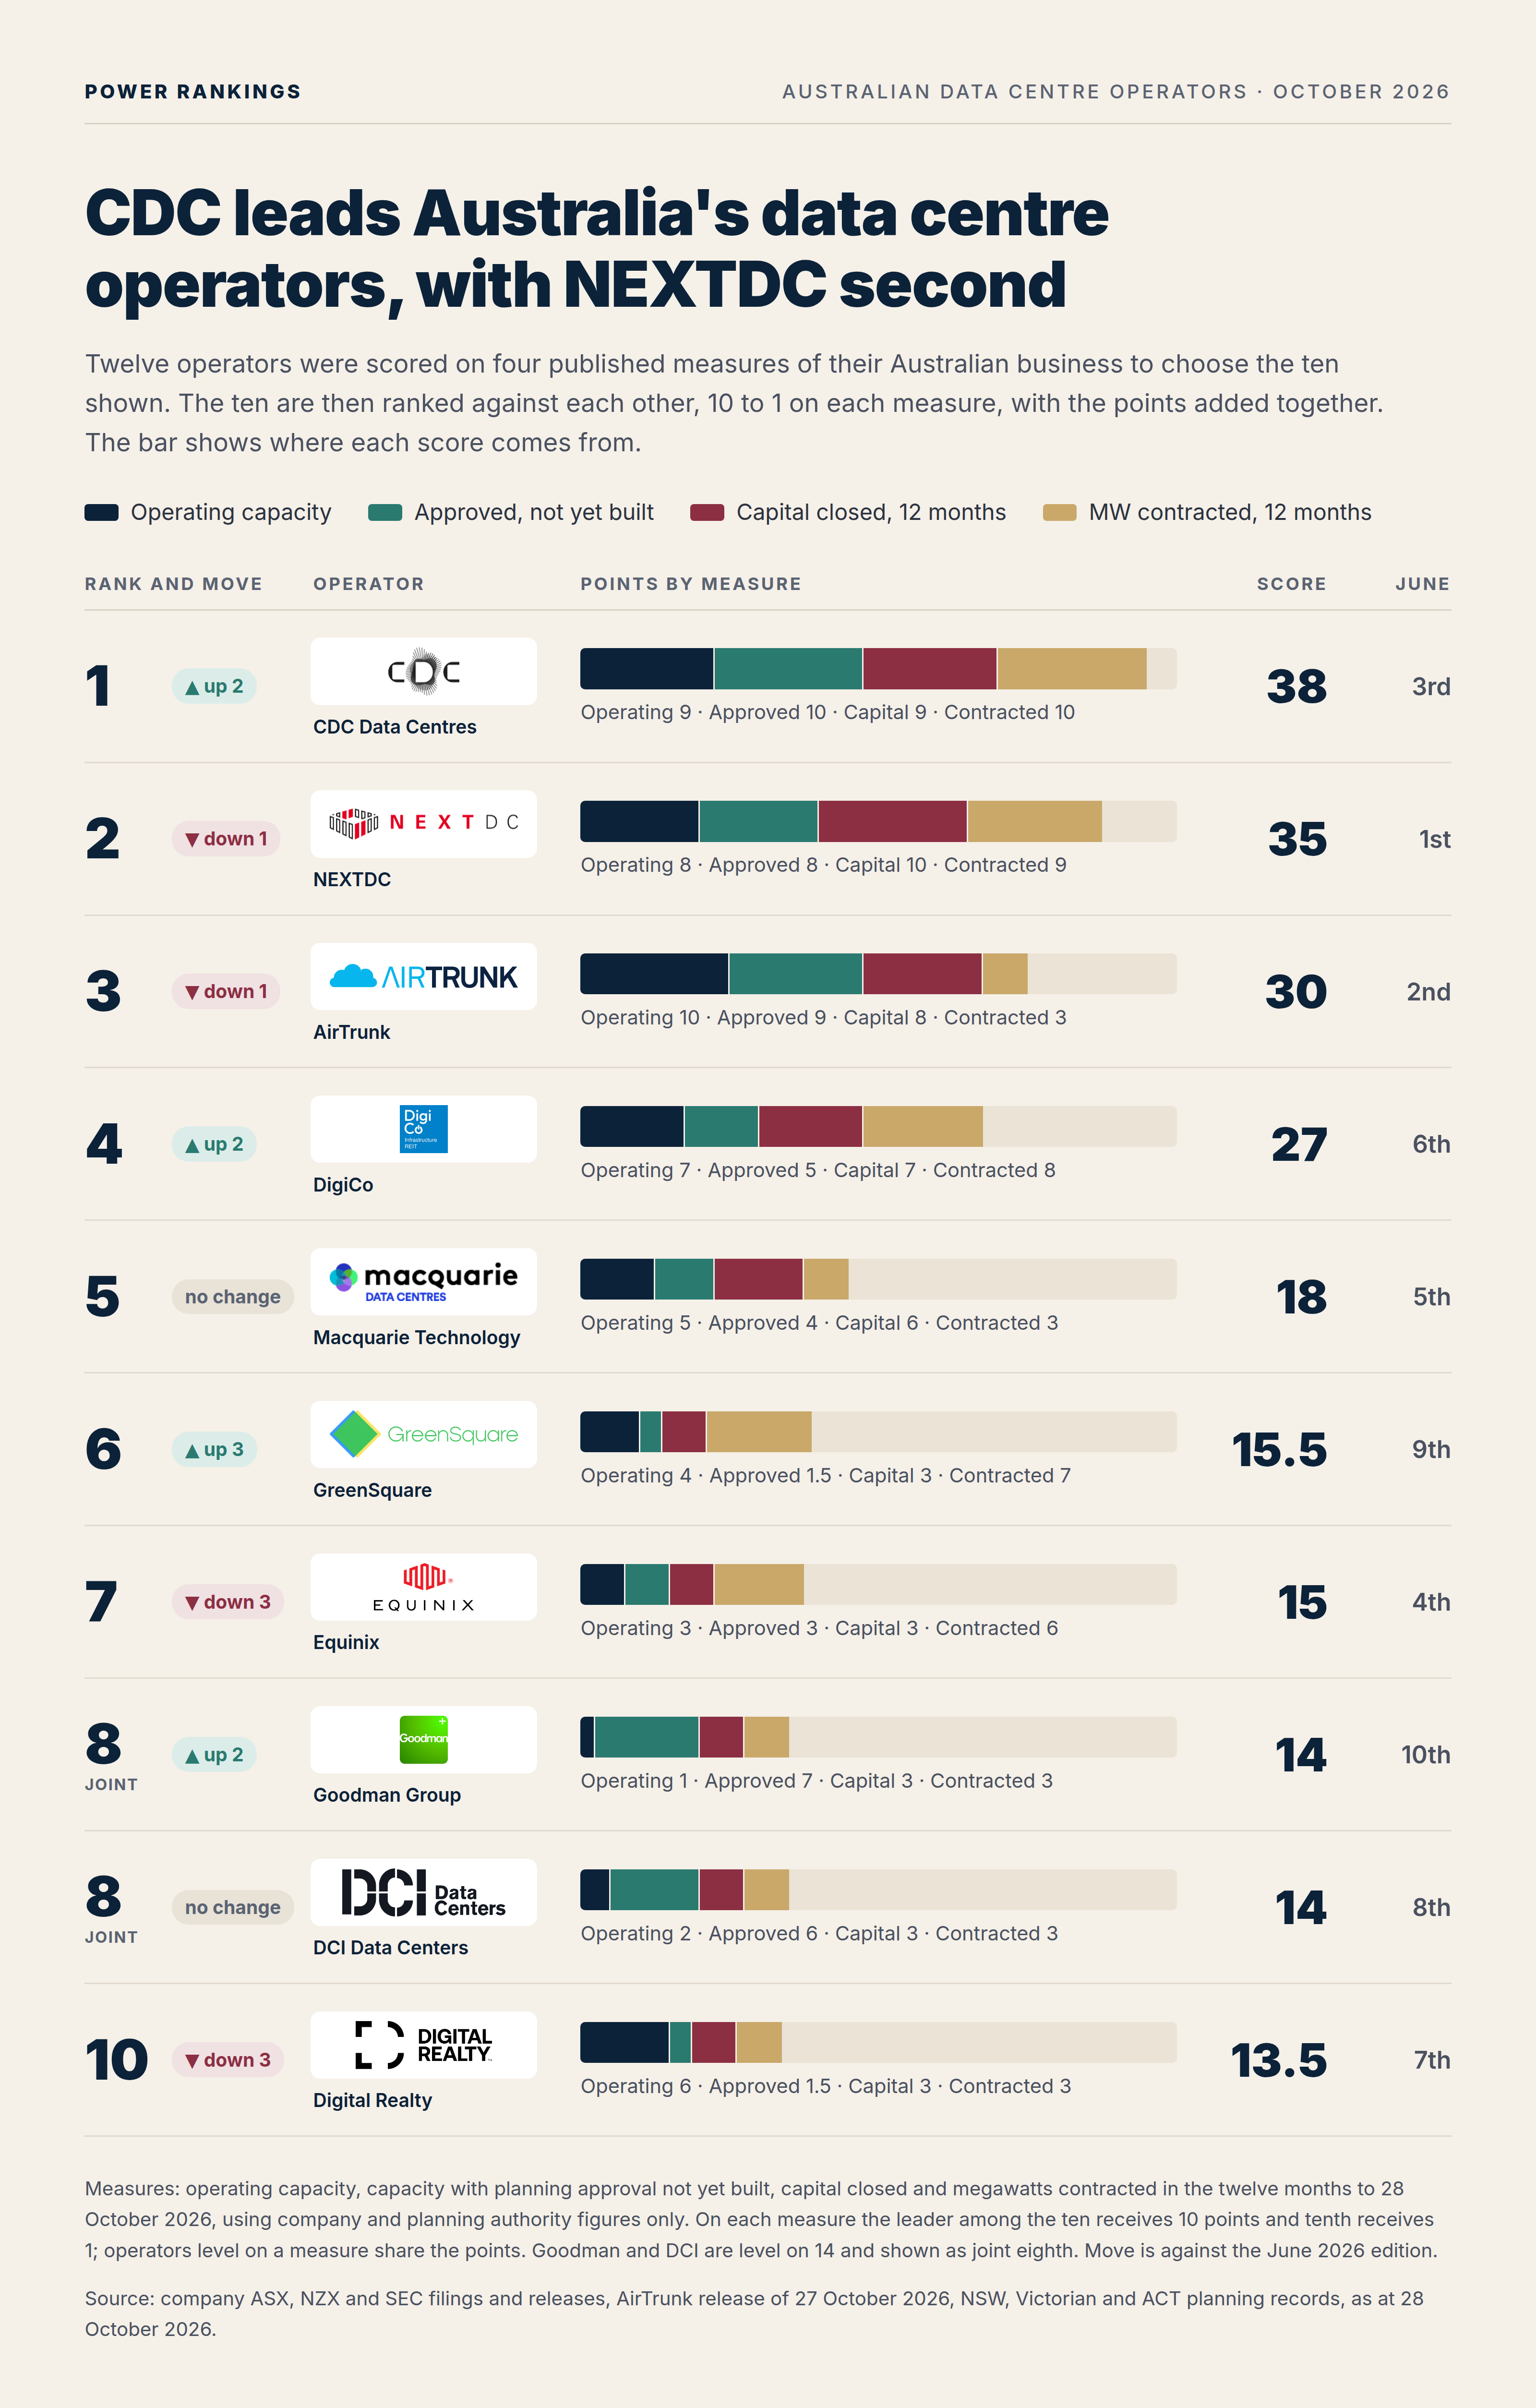
Power Rankings October 2026: CDC Data Centres, NEXTDC, AirTrunk, DigiCo, Macquarie Technology, GreenSquare, Equinix, Goodman and DCI Data Centers (joint eighth) and Digital Realty ranked on operating capacity, approved capacity, capital closed and contracted capacity, with June 2026 ranks
Source: company ASX, NZX and SEC filings and releases, AirTrunk release of 27 October 2026, NSW, Victorian and ACT planning records, as at 28 October 2026.
Four published measures decide the order
Each operator is ranked on four measures of its Australian business: capacity operating, capacity with planning approval but not yet built, capital closed in the twelve months to 28 October 2026, and megawatts contracted by customers in the same twelve months. On each measure the leader receives 10 points, second receives 9 and tenth receives 1, and operators level on a measure share the points for the places they occupy. The four results are added together. CDC’s 38 is 10 for approved capacity, 10 for contracts and 9 each for operating capacity and capital. Figures reported only in the press are not counted.
Twelve operators were scored: the ten from the June edition, plus STACK Infrastructure and Zerra DC for their large Melbourne and Queensland applications. All twelve were scored to choose the ten, and the ten were then ranked against each other, so the leader on each measure among the ten receives 10 points. STACK and Zerra sit outside the ten in this edition. GPU cloud providers such as Firmus, IREN and Sharon AI, which sell computing power to AI customers, are not ranked.
Rank and operator | Score out of 40 | June 2026 rank |
|---|---|---|
1. CDC Data Centres | 38 | 3rd, up two |
2. NEXTDC | 35 | 1st, down one |
3. AirTrunk | 30 | 2nd, down one |
4. DigiCo Infrastructure REIT | 27 | 6th, up two |
5. Macquarie Technology Group | 18 | 5th, unchanged |
6. GreenSquare | 15.5 | 9th, up three |
7. Equinix | 15 | 4th, down three |
8= Goodman Group | 14 | 10th, up two |
8= DCI Data Centers | 14 | 8th, unchanged |
10. Digital Realty | 13.5 | 7th, down three |
Source: company ASX and NZX releases and results presentations, Digital Realty financial supplement of 23 July 2026, AirTrunk release of 27 October 2026, NSW Planning Portal, Victorian ministerial permits register, ACT development application register, as at 28 October 2026.
625MW of new contracts puts CDC first
CDC ranks first on approved capacity and contracts, and second on operating capacity and capital. Part-owner Infratil, a New Zealand-listed infrastructure investor, disclosed a 555MW contract on 5 May 2026 with an unnamed United States customer with a high investment-grade credit rating. A further 70MW followed on 16 September, taking contracted capacity to 1.1GW at 30 September.
The 504MW Marsden Park campus in Sydney has held planning approval since 27 November 2025, and the ACT approved the 84MW Beard 2 building in Canberra on 29 September 2026. CDC’s capital in twelve months includes A$700 million of bonds in July and a A$1 billion bond sold privately to US investors in August.
NEXTDC ranks second on capital as M3 power moves to FY28
NEXTDC ranks first of the ten on capital closed and second on contracts. It raised A$1.5 billion of equity, a A$1 billion hybrid and A$750 million of lower-ranking debt between April and May 2026. It then closed A$2.3 billion of new bank facilities on 15 July and settled A$1.1 billion of convertible notes on 17 September. Contracted capacity reached 740MW at 30 June 2026, and liquidity stood at A$8.675 billion at 30 September.
NEXTDC paused trading in its shares on 19 October and on 21 October cut FY27 revenue guidance to A$475 million to A$500 million, from A$615 million to A$640 million. The next increase in power to M3 in West Footscray moved from FY27 to FY28. Electricity distributor Jemena has suspended parts of its network works there and does not expect to restart them before February 2027, and NEXTDC put all new development projects and land purchases on hold. The M3 capacity remains under contract and its data halls are under construction.
AirTrunk’s A$4.25 billion SYD3 loan keeps it third
AirTrunk ranks first on operating capacity, scored on the more than 755MW listed on its Australia page; its 27 October release puts the five-campus platform, including SYD3, at more than 1.2GW. It ranks second on approved capacity, from its SYD3 campus and a building at Apollo Place in Lane Cove West. AirTrunk lists SYD3 at more than 400MW. The Apollo Place building, part of its Lane Cove West campus, is approved for 45MW.
The company announced on 27 October 2026 that 32 lenders had backed a A$4.25 billion loan for SYD3, its campus at Huntingwood in Western Sydney, with completion expected by mid-2028. The loan ranks third of the ten on capital closed. Its 550.5MW Kurri Kurri application in the Hunter is open for public comment until 11 November 2026.
DigiCo’s SYD1 contract lifts it two places
DigiCo announced on 15 October 2026 a 71MW, 15-year contract at SYD1 in Ultimo with an unnamed global technology firm. The contract includes 20MW moved over from existing customers and leaves the 88MW campus fully contracted once its expansion is built. The first 10MW of that expansion is due late in FY27, the year to June 2027.
DigiCo ranks third on contracts, behind CDC and NEXTDC. It also raised its Australian loan facility from A$1.25 billion to A$1.45 billion, disclosed on 21 August 2026.
Macquarie holds fifth as GreenSquare climbs to sixth
Macquarie Technology Group holds fifth on 21MW of installed capacity and an approved IC3 Super West building under construction at Macquarie Park. Its proposed 200MW campus counts once it has planning approval.
GreenSquare rises to sixth, from ninth in June. SYD1 at Norwest, a data centre built in 1995 and rebuilt in eight months, opened on 19 October 2026 with 15MW. On 21 September the company signed Sharon AI, a NASDAQ-listed GPU cloud provider, which GreenSquare describes as SYD1’s first customer, to deploy about 8,200 NVIDIA B300 chips. It is a contract for the 15MW first stage, and it ranks GreenSquare fourth of the ten on contracts. GreenSquare could move up if the 80MW second stage at Norwest or the 240MW Spotswood campus in Melbourne is approved.
Equinix moves from fourth in June to seventh with the change of method. It ranks on 18 Australian sites, its 30MW Rosehill approval and a 4.5MW deployment in Sydney for AI chipmaker Groq. Its third-quarter results are due on 29 October 2026, Sydney time.
Goodman and DCI share eighth place
Goodman rises from tenth to joint eighth with DCI, and its approved capacity ranks fourth of the ten. It won approval for Project Pluto at Guildford West on 23 July 2026 and Project Apollo at Macquarie Park on 2 September, and withdrew Project Mars at Lane Cove West on 28 September.
DCI Data Centers, owned by Brookfield, holds eighth, level with Goodman. NSW approved more power for its SYD02 expansion at Eastern Creek on 5 August 2026, taking it to 63MW on DCI’s figures, and approved its 25.4MW Poplars campus at Jerrabomberra, near Canberra, on 6 November 2025. DCI operates SYD01 at Eastern Creek and two Adelaide sites at Kidman Park.
Digital Realty is tenth, from seventh in June. Its financial supplement for the quarter to 30 June 2026 shows 30MW of IT load across four Sydney data centres, up from 23MW three months earlier, and it also operates MEL11 at Deer Park in Melbourne. Its third-quarter results are due on 30 October 2026, Sydney time.
What to watch
NEXTDC’s annual meeting on 20 November 2026, where the board will report the outcome of its review of spending plans.
Public comment on AirTrunk’s Kurri Kurri application, closing on 11 November 2026.
Goodman’s Australian data centre development partnership, which it expects to establish in the first half of FY27.
The next edition in February 2027.
Keep reading the market
Get The Strategic Brief in your inbox every Thursday.
The leading Australian data centre and AI infrastructure newsletter.
Your Next Read
Data Centres Australia Excellence Awards 2026 winners
Top Data Centre Operators in Australia 2026: NEXTDC Leads the Pack
NEXTDC renews its board and Scroggie forgoes FY27 bonuses
Latest Headlines
AirTrunk raises A$4.25 billion and plans A$75 billion more in Australia
27 Oct 2026SCX.ai joins SpaceX's Grok partner network
27 Oct 2026NVIDIA GPU rental prices set to stay high into early 2027
27 Oct 2026Australian AI companies pay 6% to 10% on GPU loans
27 Oct 2026Four predictions for Australia as NVIDIA puts AI factories in containers
26 Oct 2026
Interested in reaching this audience? Advertise with us.