DXN shares fall 47% as first US AI customer moves to cancel
By Winston Su, Editor · · Add us as a preferred source on Google
At a glance
DXN shares fell 47 per cent to 14 cents on 30 October 2026 after the modular data centre maker's first AI customer moved to cancel an A$8.8 million contract.
The customer, a US-listed neocloud, cited a strategic shift in its own business, and DXN expects about A$4.2 million for work done and costs committed.
A follow-on campus program, which DXN had put at more than US$200 million in revenue, is unlikely to proceed.
The same quarterly report showed revenue up about 380 per cent and DXN's second AI contract, for a 2MW facility, on track for early 2027.
Even after the fall, the stock closed at almost seven times its 2.1 cent price before the June contract.
DXN's shares nearly halved on 30 October 2026 after its first AI customer, a US-listed neocloud (a company that rents out AI computing power), moved to cancel an A$8.8 million AI high-performance computing (HPC) order. DXN said in its September quarter report and investor presentation that the customer told it after the quarter ended that "following a strategic shift in its business, it intends to cancel" the contract.
DXN, listed on the ASX since April 2018, describes itself as a vertically integrated manufacturer and operator of modular data centres across Asia Pacific. It builds prefabricated data centres and cable landing stations, the buildings where subsea cables come ashore, for government, telecommunications, mining, defence and subsea cable customers. It also runs its own data centre in Darwin, having sold its Hobart site in June 2026, and reported A$10.1 million of revenue for the year to 30 June 2026. The June AI contract was worth more than DXN's whole market value of about A$6.6 million at the time, according to Stocks Down Under.
DXN's quarterly report also showed September quarter revenue up about 380 per cent on a year earlier, to about A$3.4 million, and a larger order book. The report said the campus program the customer had flagged in June is unlikely to proceed. DXN's second AI contract, for a 2MW facility, is on track for early 2027.
DXN's market value fell to about A$53 million
The shares traded between 11.5 and 16 cents on 30 October, according to Market Index. Volume reached 62.3 million shares, about 12 times the four-week daily average. The fall took about A$47 million off DXN's market value, which ended the day at about A$53 million.
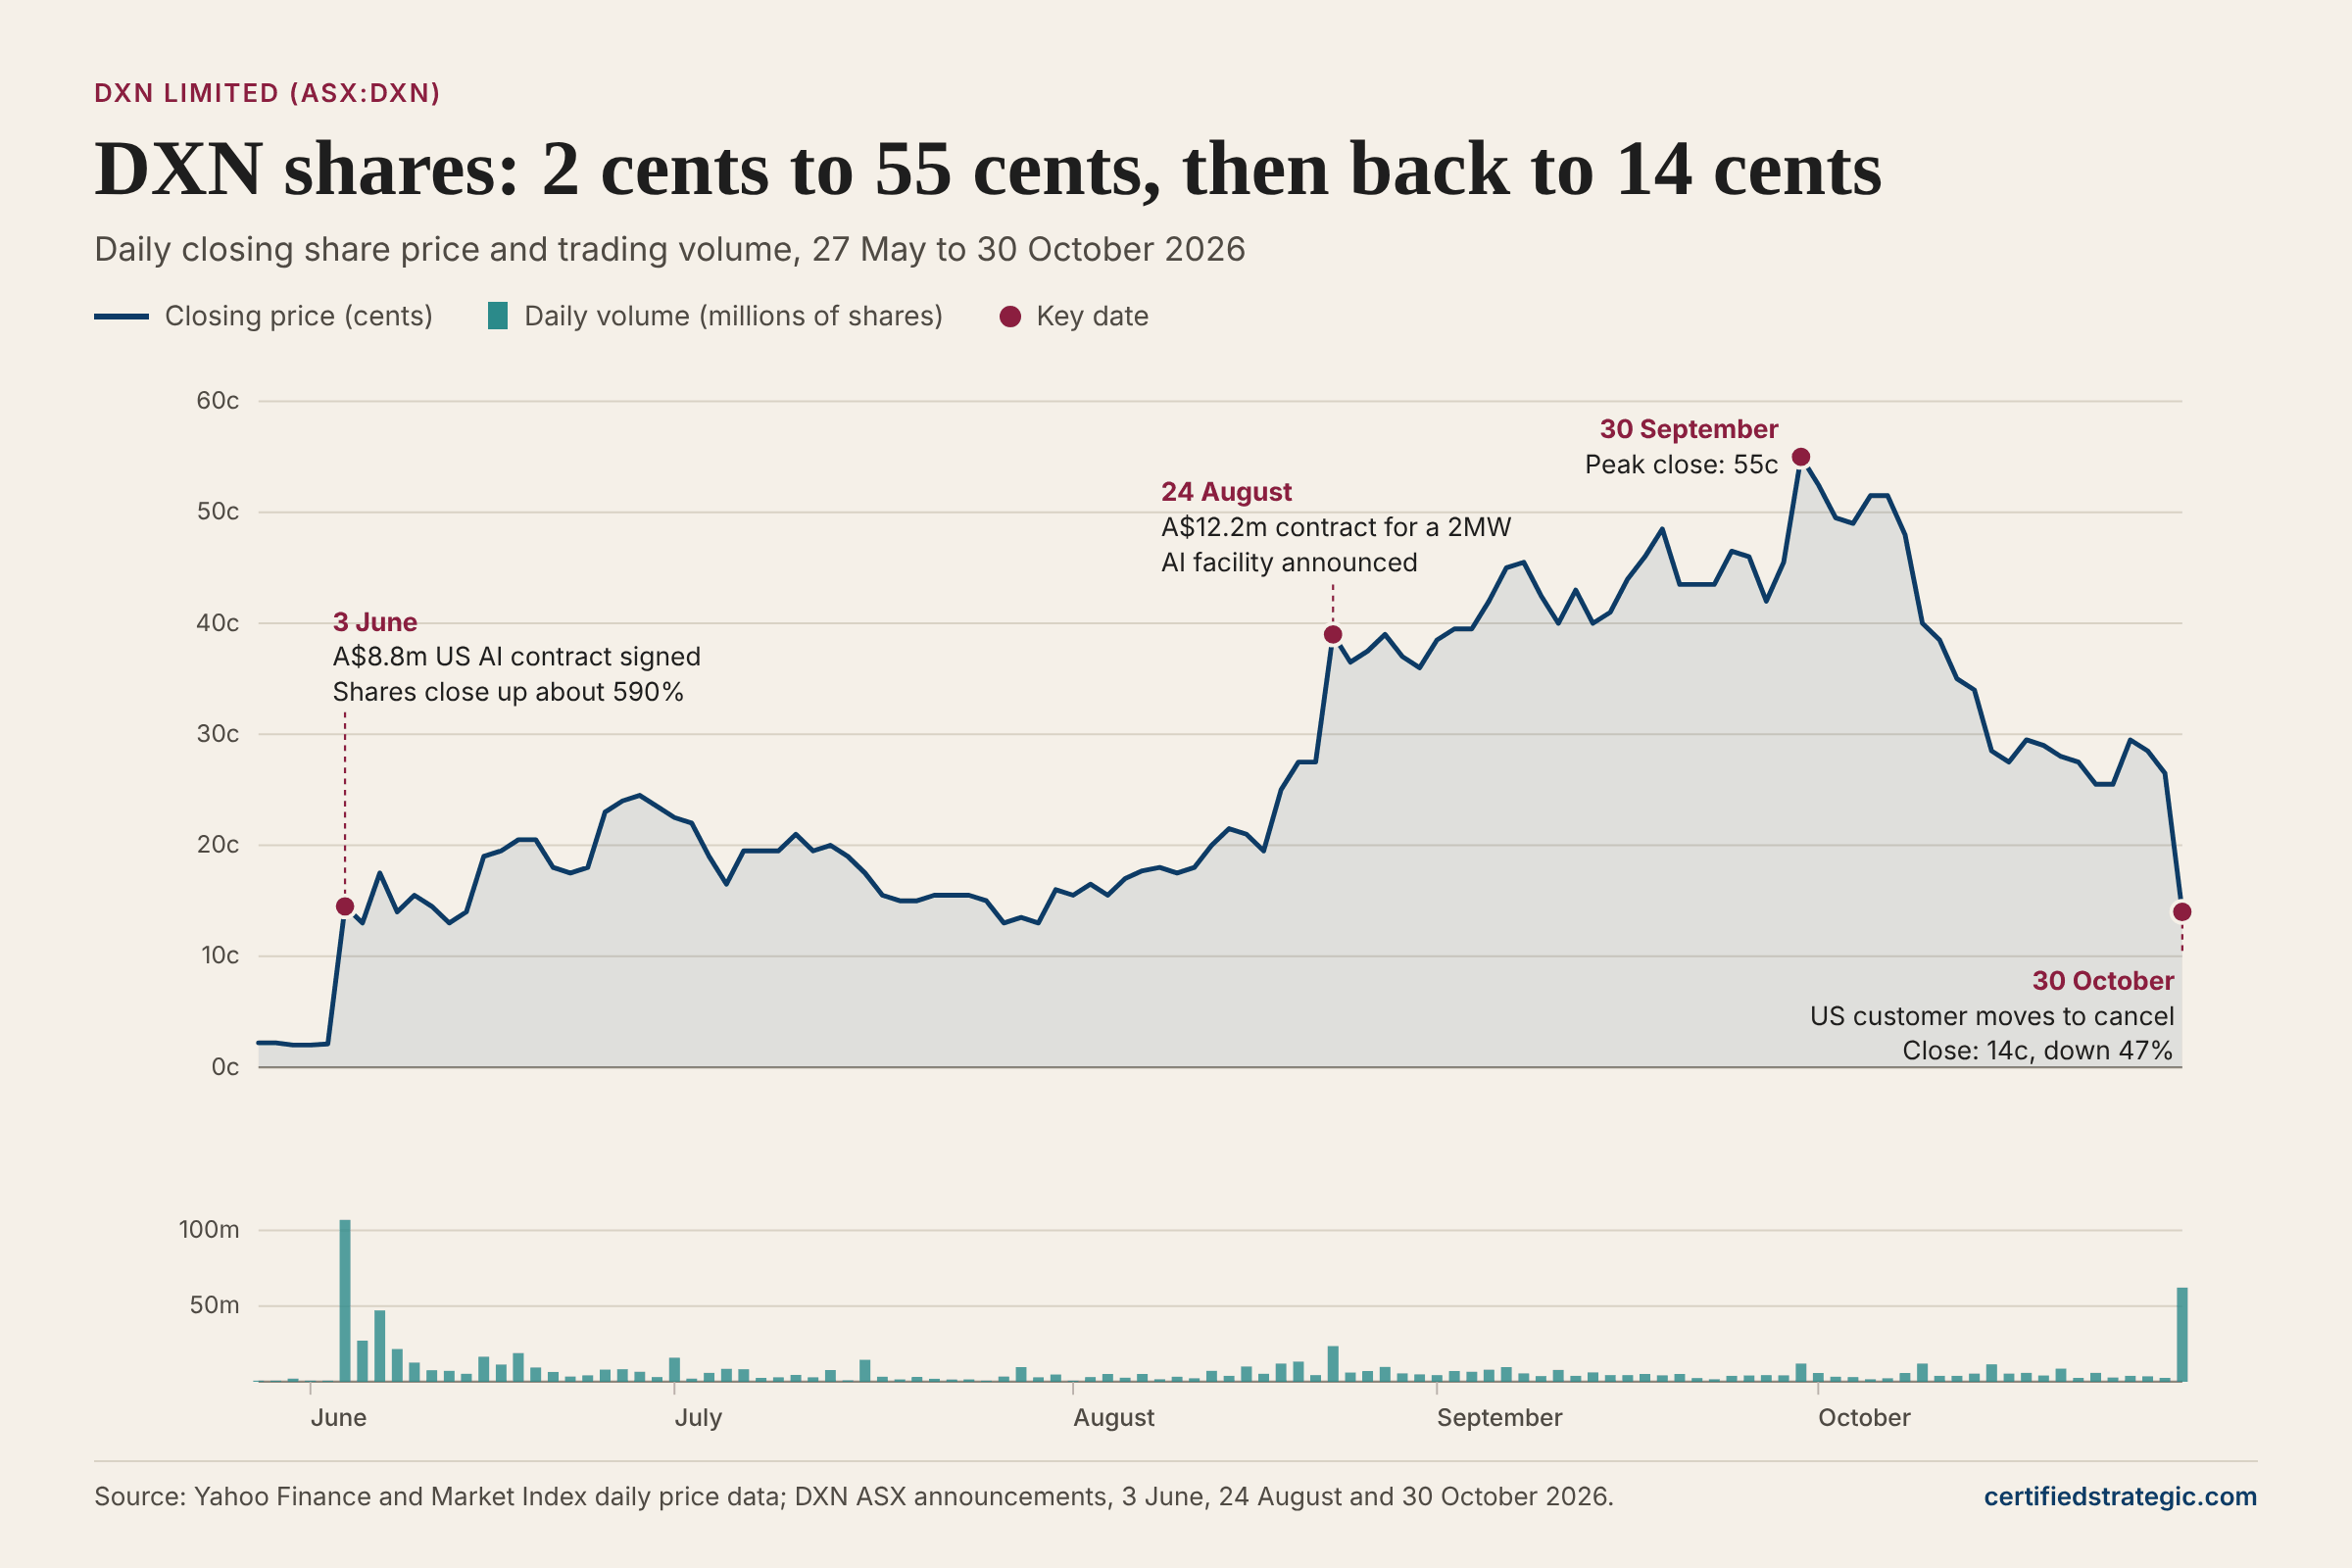
DXN traded at 2.1 cents before it announced the contract on 3 June, and closed up about 590 per cent that day. The shares closed at a peak of 55 cents on 30 September and at 26.5 cents on 29 October. They remain up about 259 per cent for 2026.
DXN expects A$4.2 million from the contract
The A$4.2 million, 48 per cent of the contract value, covers work completed and costs committed, amounts DXN says the customer has not disputed. DXN recognised A$0.1 million of revenue from the job in the September quarter "as work progressed and parts were ordered". The cancellation has not been finalised.
The cancellation cut about A$8.6 million from DXN's order book. With more than A$19 million of new contract awards in the quarter, backlog still rose to A$30.8 million at 30 September, from A$23.5 million at 30 June.
Chief executive and managing director Shalini Lagrutta said DXN was "disappointed that our maiden AI HPC customer has changed its strategic direction" but that "our contract terms have protected DXN's position".
The campus program is unlikely to proceed
When DXN signed the contract on 3 June, it described a 1.36MW AI data centre to be fabricated at its Welshpool factory in Western Australia and commissioned at the customer's US mainland site within about six months of signing.
The customer had indicated it intended to progress to a campus-scale program, a follow-on revenue opportunity DXN put at more than US$200 million over one to two years from June. As part of its strategy shift, the customer "is unlikely to proceed with the larger follow-on campus opportunity", the quarterly report says.
The 2MW contract is DXN's next AI delivery
DXN's second AI contract, an A$12.2 million order announced on 24 August with an unnamed AI compute operator, covers a 2MW facility that combines new DXN modules with upgraded infrastructure on the customer's site. Lagrutta said when the deal was announced that DXN was chosen "because the requirement is one that conventional construction cannot meet within the timeframe".
Detailed design and long-lead procurement for the job were finalised by 30 September, and DXN has started building the modules at its Seven Hills facility in Sydney. DXN expects the customer's site to be operational in early calendar 2027. DXN says its factory-built modules can be deployed in about five to eight months from signing. NVIDIA's DSX POD design takes a similar approach, with partners building and testing AI factory pods inside shipping containers before they reach site.
DXN is likely to be judged on its next AI contract
With the first contract heading for cancellation, DXN is likely to be judged over the next six months on whether it delivers the 2MW facility on schedule and converts its pipeline into a new AI order. DXN counts 93 identified projects, says their combined value rose 115 per cent on the June quarter, and puts 13 per cent of opportunities in final negotiations or at verbal win or contracting stage. About 28 per cent of the pipeline relates to global AI compute infrastructure customers.
Net operating cash flow was negative A$4.7 million in the September quarter, which DXN says would have been stronger had delayed customer receipts arrived as scheduled.
What to watch
Final cancellation terms. DXN will update investors once the cancellation is finalised.
The Seven Hills build. DXN describes the 2MW facility as the first phase of a potentially larger deployment.
Cash and first-half revenue. DXN held A$11.1 million in cash on 28 October, up from A$6.4 million at 30 September. It expects A$11.0 million of revenue in the six months to 31 December 2026.
Keep reading the market
Get The Strategic Brief in your inbox every Thursday.
The leading Australian data centre and AI infrastructure newsletter.
Your Next Read
What Firmus's pulled IPO means for Tasmania and Maas Group
CDC ends its 1.6GW rollout with Firmus at 42MW in Melbourne
Firmus' Melbourne AI factory now runs customer models
Latest Headlines
Alphabet loses nearly US$500bn as AI spending climbs
31 Oct 2026Approval waits put the 3.9GW data centre forecast at risk
31 Oct 2026SCX.ai CEO: AI inference doesn't need new data centres
30 Oct 2026Albanese plans a ban on suburban data centres
30 Oct 2026Dover's 200MW South Morang data centre awaits a federal ruling
30 Oct 2026
Interested in reaching this audience? Advertise with us.